Issue ATOL Immediately: Travel Payment Plans for White Label Agents
Step by step compliance checklist for white label agents launching travel payment plans. Map CAA and FCA rules, automate ATOL certificates.
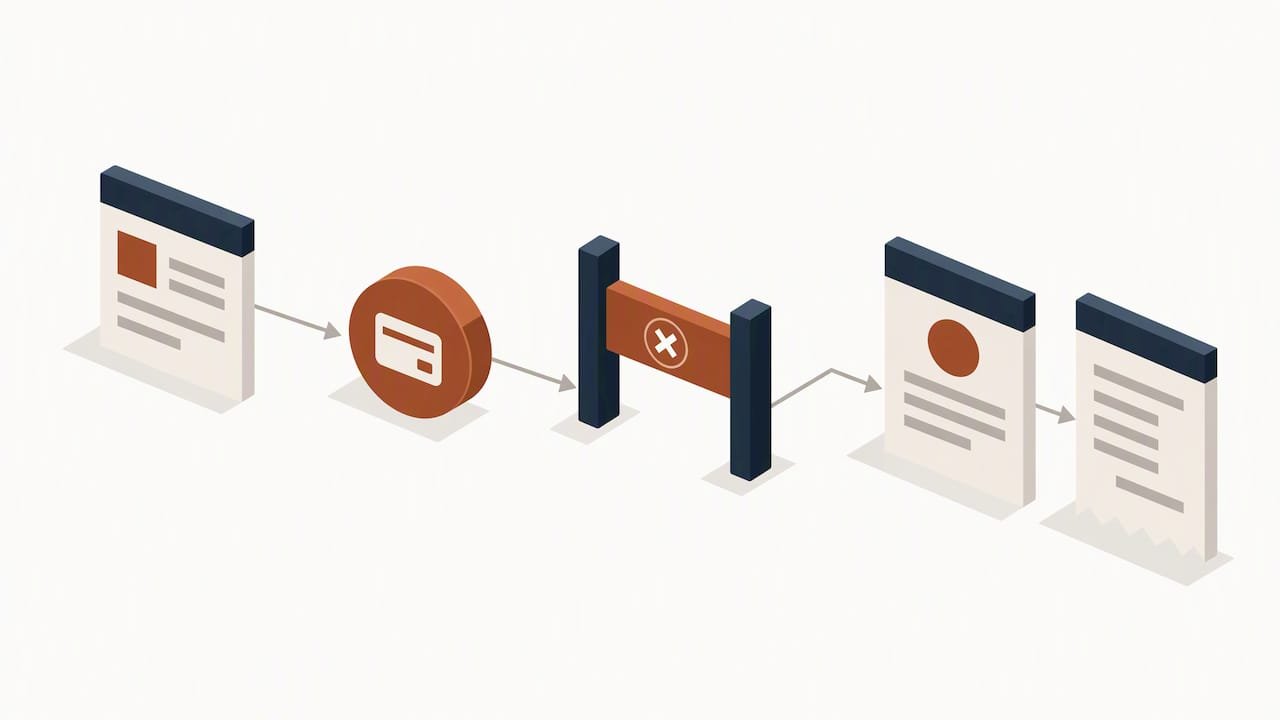
A travel booking payment plan, in a white-label agency context, is a customer-facing deposit and instalment workflow sitting on top of your principal’s ATOL licence. The moment you take any payment, however small, you must issue an ATOL Certificate and a receipt that states clearly which money is protected. Before you launch, confirm in writing who holds the funds at each stage and check that your agency agreement and your platform’s payment flow actually match what you tell customers.
TL;DR:
- Payments must trigger immediate issuance of an ATOL Certificate, with clearly identified protected amounts from the first deposit onward.
- Agency agreements should specify who produces certificates, who holds the funds, and how insolvency security covers deposits and lead times.
- Routing funds correctly is crucial to stay outside regulated payment services, requiring explicit collection “on behalf of” the ATOL holder without pooling customer payments.
- Small-scale pilot testing is recommended to track booking flow, certificate issuance, and error rates before scaling instalment plans widely.
- Using automated documentation and clear messaging supports compliance and enhances customer confidence, which can increase booking values and partner earnings.
Table of Contents
- Setting up your platform and contracts before you sell instalments
- Why ATOL timing and Regulation 19 shape how you design instalments
- Choosing between deposits, in-house instalments and BNPL
- Designing payment flow so you stay inside the commercial-agent exclusion
- Building the receipts, audit trail and message templates that keep you covered
- Testing instalment plans before you scale them
- What rolling out instalments actually teaches you as a partner
- How TimesHunters supports compliant instalment plans
- FAQ
- Sources
Setting up your platform and contracts before you sell instalments
Get the paperwork and the plumbing right before you take a single deposit. Your agency agreement needs to say, in plain terms, who issues the ATOL Certificate, who holds protected money and what happens if a payment is missed.
Decide the commercial terms first:
- Deposit size and minimum deposit amount.
- Instalment frequency, such as monthly, milestone-based, or linked to departure date.
- Final balance due date, usually a few weeks before travel.
- Refund and cancellation rules for each instalment stage.
Then map the system side:
- Confirm which account actually collects each payment.
- Assign who issues the receipt and the ATOL Certificate.
- Set automated reminders for upcoming instalments.
- Build a receipt template that separates protected and non-protected sums.
A receipt that does not name the ATOL holder is a compliance gap, not a formality.
Why ATOL timing and Regulation 19 shape how you design instalments
The regulatory baseline is simple to state and easy to get wrong in practice. The Civil Aviation Authority requires an ATOL Certificate to be issued immediately when any consumer payment is taken, not only once a booking is paid in full. Receipts must identify which part of the payment is ATOL-protected, which means your very first deposit receipt needs that detail built in from day one.
Your agency agreement should reflect the ATOL Standard Terms and name the ATOL holder explicitly, with a clear record of who is responsible for producing each Certificate. Under Regulation 19 of the Package Travel and Linked Travel Arrangements Regulations 2018, organisers must provide insolvency security that accounts for down payments and the gap between an early deposit and the travel date, since a long lead time increases the amount of customer money sitting exposed at any one point.
Run these checks with your platform provider or legal counsel before launch:
- Confirm the Certificate issuance trigger fires on first payment, not final payment.
- Check receipt templates display protected sums correctly.
- Verify the agency agreement names the current ATOL holder.
- Ask how insolvency security is calculated against your typical deposit and lead times.
Choosing between deposits, in-house instalments and BNPL
The payment structure you choose affects both compliance exposure and how much control you keep over the customer relationship.
A deposit-plus-balance model is the simplest route: the principal handles protected funds directly, and your regulatory footprint stays small. Platform-managed instalments give you more control over the customer relationship, but you need to be certain the funds routing does not tip you into regulated payment-services territory. Third-party buy-now-pay-later providers convert bookings quickly, but they bring their own fees and can sit awkwardly against ATOL fund-protection rules if the money never passes through the protected structure correctly.
Before integrating any option, check:
- How reconciliation works between the provider and your booking records.
- What fees apply per instalment or per transaction.
- How chargebacks and disputes are handled and by whom.
- What disclosures customers see about who they are actually paying.
Pro Tip: Pilot one payment method at a time rather than launching deposits, instalments and BNPL together, so you can isolate which one is actually driving conversion.
Designing payment flow so you stay inside the commercial-agent exclusion
How you route money determines your regulatory status as much as what you call the product. The FCA’s commercial-agent exclusion applies only where you act for either the payer or the payee, never both at once. The moment you control pooled customer funds before passing them on, you risk falling outside that exclusion and into regulated payment-services territory.
To keep your flow clean:
- Collect payments explicitly “on behalf of” the ATOL holder, never into an account you control as a trading party.
- Avoid pooling customer instalments in an account you hold before onward transfer.
- Document, in the contract and in the platform’s technical setup, exactly who legally owns each payment at each step.
- If your current flow implies regulated payment services, speak to your principal or a compliance adviser immediately and adjust routing before taking further payments.
Getting this wrong does not just risk a fine. It can undermine the very protection your customers believe they are buying.
Building the receipts, audit trail and message templates that keep you covered
Every booking needs a paper trail that would survive scrutiny if the ATOL holder ever failed. Receipts and confirmations should show the ATOL holder’s name, the ATOL number, the protected amount and a unique Certificate reference.
- Timestamp every payment, every transfer to the principal and every Certificate issued.
- Keep a single booking-level record linking payments to communications.
- Separate service messages (payment confirmations, missed-payment alerts) from marketing follow-ups, with distinct templates and consent records under PECR and ICO guidance.
- Record how missed instalments and refunds are handled, including any pipeline monies still in transit to the principal.
The CAA can require booking-level evidence to assess a consumer claim after an ATOL holder failure, so incomplete records can delay or weaken a customer’s claim.
Testing instalment plans before you scale them
Launch small, measure properly, then expand. Before opening instalments to every customer, track checkout completion rate, drop-off by device, instalment acceptance rate, dispute rate and reconciliation errors across a defined pilot.
- Run an ABTA-style test varying deposit size and instalment cadence against basket value.
- Vary the order payment options appear in by device type, since mobile and desktop behaviour differ.
- Set a minimum launch criterion: Certificates issuing correctly on every live transaction before scaling.
- Define a rollback trigger: pause instalments immediately if documentation fails on even one booking.
ABTA’s benchmarking frames payment choice as something to test rather than offer indiscriminately, matching visibility and option ordering to basket value and device rather than showing every method by default.
Pro Tip: Review your audit trail weekly during a pilot, not monthly. Certificate and receipt errors are far cheaper to fix when caught on booking five than booking five hundred.
What rolling out instalments actually teaches you as a partner
Instalment plans change the shape of every conversation with a customer, not just the final invoice. The partners who get the most from them treat compliance as part of the sales pitch, not a back-office afterthought, because a customer who sees a clear, protected payment schedule books with more confidence.
One partner’s documented uplift, from £400 to £1,200 per booking, shows what happens when the groundwork is right and the commission structure rewards it properly, as seen in various travel booking payment plans with flexible payment options. Automated booking management and wholesale rates do the heavy lifting behind that kind of result, leaving the partner free to manage the relationship rather than the paperwork.
— Sam
How TimesHunters supports compliant instalment plans
We built our white-label travel agency platform so partners spend their time selling, not chasing Certificates. Our structure keeps ATOL coverage with Times Travel group’s licences, automates documentation at the point of payment and manages the funds flow behind every instalment.
- ATOL-protected licences sit behind every booking you take.
- Automated booking management issues receipts and Certificates without manual chasing.
- Partners keep a higher commission on bookings than is typical of online travel agencies.
Have a look at our white-label travel agency page to see how the platform handles the operational detail covered above, then get in touch to join the partner programme.
FAQ
What is a travel booking payment plan for white-label agents?
It is a customer-facing deposit and instalment workflow that a partner agent offers on top of a principal’s ATOL licence. The key trigger is that an ATOL Certificate must be issued the moment any payment, including a small deposit, is taken.
Who is responsible for issuing the ATOL Certificate on an instalment booking?
The agency agreement should name the ATOL holder and state explicitly who produces the Certificate. Under CAA guidance, the Certificate must be issued immediately on first payment, not deferred until the balance is settled.
Does taking instalment payments change our regulatory status?
It can. The FCA’s commercial-agent exclusion only applies where you act for either the payer or the payee, so controlling pooled customer funds before passing them on may take you outside that exclusion and into regulated payment-services territory.
How much commission do partners earn through TimesHunters?
Pricing for the platform itself is available on request.
Can we send automated payment reminders without breaching marketing rules?
Yes, provided service messages like payment reminders are kept separate from promotional marketing, with their own templates and consent records under ICO PECR guidance. Marketing follow-ups need affirmative consent, while operational messages do not.